The Fed is cautious about inflation, yet mortgage rates recently declined. Discover why and what it means for homebuyers, refinancing, and investors.
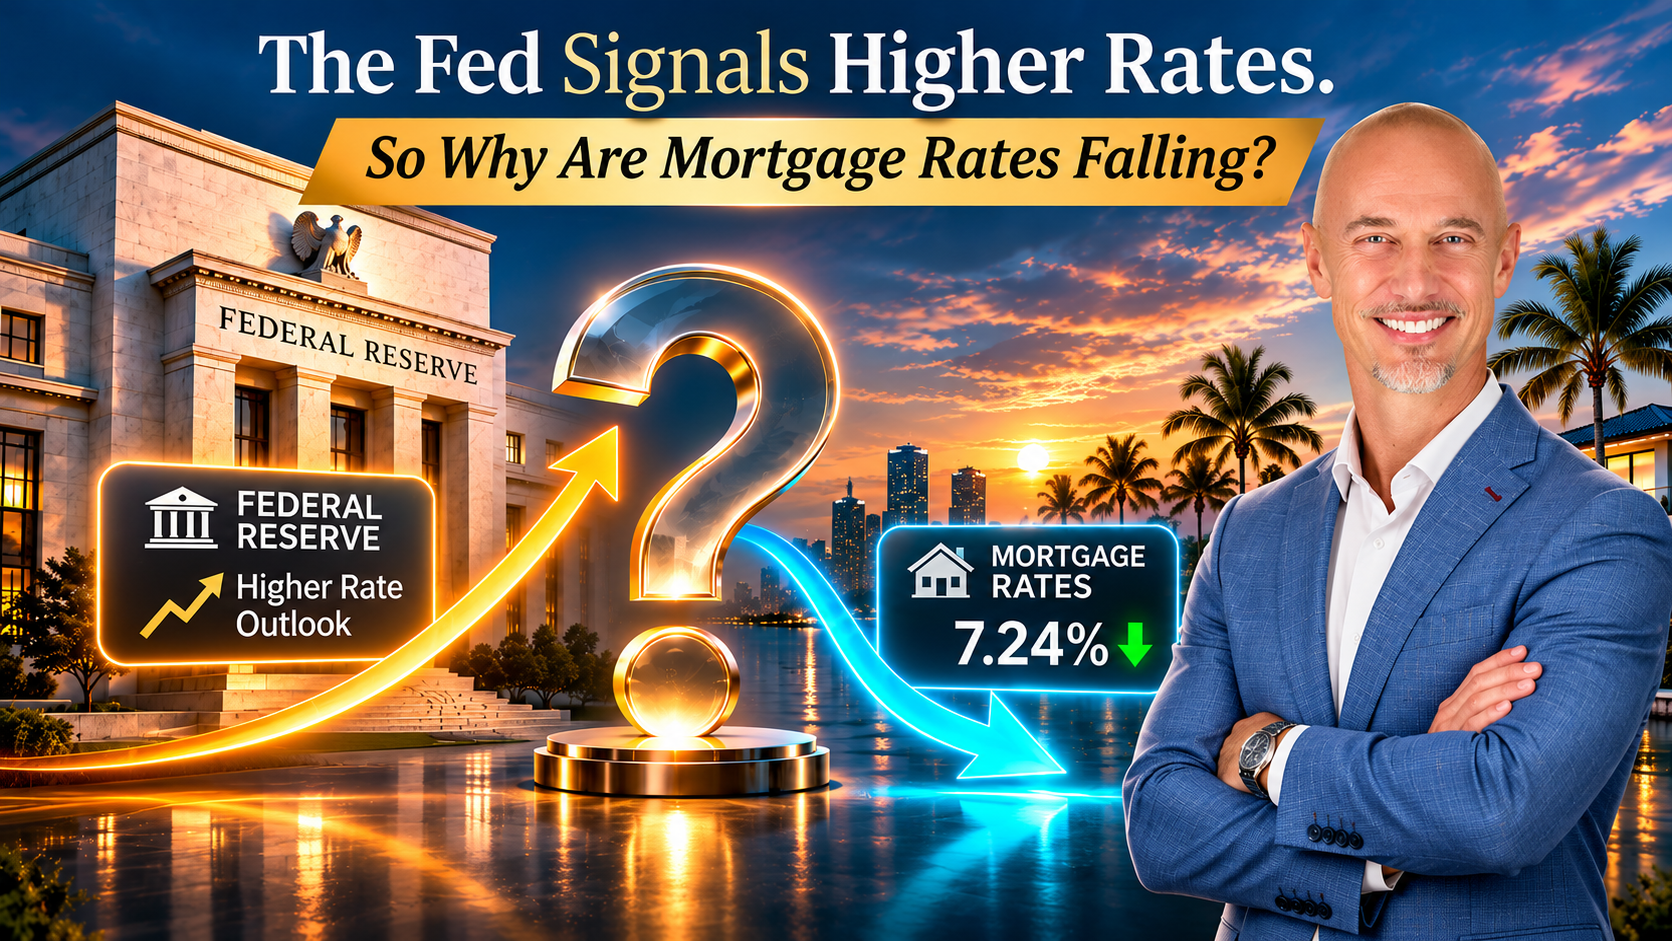
The Fed Holds Rates Steady. So Why Are Mortgage Rates Falling?
November 2, 2026 | Mortgage Market Insights by Chris Pessy
The Federal Reserve remains cautious about inflation, yet mortgage rates have recently moved lower. For homebuyers, homeowners, and real estate investors, that distinction could create meaningful opportunities.
The Fed held its benchmark interest rate steady at its October meeting, while the average 30-year fixed mortgage rate recently declined to 7.24%, according to the Freddie Mac figures referenced in our latest market update.
At first glance, that may seem contradictory. But understanding why these rates move differently can help you make more informed financing decisions.
1. Why Mortgage Rates Don't Follow the Fed Directly
One of the most common misconceptions is that mortgage rates automatically rise or fall whenever the Federal Reserve changes its benchmark rate.
They don't.
The Fed primarily influences short-term borrowing costs. Mortgage rates are more closely influenced by:
- Treasury yields: Particularly the 10-year Treasury, an important benchmark for long-term mortgage pricing.
- Mortgage-backed securities: Investor demand and market pricing directly affect mortgage rates.
- Inflation expectations: Expectations of lower inflation can support lower long-term yields.
- Economic conditions: Employment, consumer spending, and growth expectations influence investor behavior.
The takeaway: Mortgage rates can decline even when the Fed maintains a cautious position on inflation.
2. What Lower Mortgage Rates Mean for Homebuyers
Even modest improvements in mortgage rates can influence purchasing power.
Consider a hypothetical $750,000 mortgage with a 30-year fixed term:
Interest RateMonthly Principal & Interest7.50%$5,2447.00%$4,9906.50%$4,741
A reduction from 7.50% to 6.50% represents approximately $503 in monthly savings, or more than $6,000 annually.
These examples exclude property taxes, insurance, HOA fees, and other housing expenses.
For buyers, the opportunity isn't simply securing a lower rate. It's understanding how financing, property selection, and negotiating leverage work together.
3. Florida and California: Two Different Markets
Real estate remains highly localized.
South Florida
Buyers in certain condominium markets may benefit from increased inventory and greater negotiating flexibility, particularly when sellers are motivated.
This can create opportunities to negotiate purchase prices, closing-cost contributions, or temporary rate buydowns.
California
In supply-constrained markets, particularly desirable neighborhoods throughout the Bay Area and Southern California, limited inventory can continue to support competition for well-positioned properties.
Here, financing preparation and the ability to close efficiently can be just as important as the interest rate.
My perspective: The strongest opportunities emerge when buyers evaluate financing conditions alongside local market dynamics.
4. Exclusive Mortgage Opportunity: 5.875% 7/6 ARM
5.875% Initial Interest Rate | 6.40% Estimated APR | Zero Discount Points
At United American Mortgage Corporation, we're highlighting an exclusive financing opportunity for qualified homebuyers.
Program highlights:
- 5.875% initial interest rate
- 6.40% estimated APR
- 7/6 Adjustable-Rate Mortgage
- 30-year amortization
- Initial interest rate fixed for seven years
- Rate adjustments every six months after the initial seven-year period
- Zero discount points
How Does a 7/6 ARM Work?
A 7/6 ARM provides a fixed initial interest rate for the first 84 months. After that period, the rate may adjust every six months based on the applicable index plus margin, subject to contractual rate caps.
This financing structure may appeal to buyers who value a predictable initial rate for seven years and want to evaluate alternatives to traditional fixed-rate mortgages.
However, after the initial fixed period, both the interest rate and monthly payment may increase. Borrowers should evaluate the potential payment adjustments when comparing financing options.
Interested in qualifying?
Simply contact me and mention “5.875% ARM” for a personalized financing review.
5. Should Homeowners Consider Refinancing?
For homeowners who purchased or refinanced when rates were higher, changing market conditions may justify another look at their financing.
But refinancing isn't simply about obtaining a lower advertised rate.
A proper analysis should consider:
- Monthly payment savings: How much could refinancing reduce your payment?
- Closing costs: How long would it take to recover the expenses?
- Loan structure: Would a fixed-rate or adjustable-rate mortgage better fit your goals?
- Long-term strategy: How long do you expect to retain the property and mortgage?
In some cases, refinancing can improve monthly cash flow. In others, maintaining the existing mortgage may be the better financial decision.
The right answer depends on the numbers.
6. Why Waiting for the Perfect Rate Can Be Costly
Trying to predict the absolute bottom in mortgage rates is difficult.
While waiting for rates to decline further, buyers may encounter changes in property prices, inventory, competition, or lending requirements.
Rather than focusing on a specific interest-rate target, consider three questions:
- Does the property make financial sense at today's price?
- Can the financing be structured comfortably within your budget?
- Would a future refinancing opportunity improve the economics?
A sound purchase should work with today's financing—not depend on an uncertain future rate reduction.
7. Chris's Market Perspective: Strategy Over Speculation
After more than 25 years in mortgage lending and real estate, one principle remains consistent:
The best financing decision isn't necessarily the one with the lowest advertised rate. It's the one that best supports your financial objectives.
Whether you're buying a primary residence, evaluating a luxury property, refinancing, or expanding an investment portfolio, the right strategy requires understanding the complete financial picture.
At UAMCO, we work with an extensive network of lending partners to evaluate conventional, jumbo, adjustable-rate, and specialized financing solutions.
The objective is straightforward: help you make an informed decision based on your circumstances and the opportunities available today.
Let's Review Your Options
Considering a purchase, refinance, or investment property?
Contact Chris Pessy for a personalized mortgage consultation.
If you're interested in the exclusive 5.875% 7/6 ARM opportunity, mention “5.875% ARM” when reaching out.
Chris Pessy
SVP of Mortgage Lending | United American Mortgage Corporation
Global Real Estate Advisor, CIPS® | Compass
25+ Years of Experience | 150+ Lending Partners
NMLS #208346 | UAMCO NMLS #1942
Mortgage Advertising Disclosures
ADVERTISEMENT — NOT A COMMITMENT TO LEND.
As of November 2, 2026. Advertised terms are based on a $1,000,000 loan amount, 30-year amortization, and a 7-Year Adjustable-Rate Mortgage (7/6 ARM), with an initial interest rate of 5.875% and an estimated Annual Percentage Rate (APR) of 6.40%, subject to verification. The initial interest rate is fixed for 84 months and may adjust every six months thereafter based on the applicable index plus margin, subject to contractual rate caps. The interest rate and monthly payment may increase after the initial fixed-rate period.
Advertised terms are available to qualified borrowers and depend on creditworthiness, loan-to-value ratio, occupancy, property type, loan amount, income, assets, and underwriting approval. Estimated underwriting and processing fees total $3,190, with zero discount points. The $999 appraisal fee is excluded from this fee total. Additional closing costs may apply. Monthly principal and interest payments exclude property taxes, insurance, and applicable HOA dues.
Rates and terms are subject to change without notice until locked. This advertisement does not constitute a loan approval or commitment to lend. Not all applicants will qualify. United American Mortgage Corporation (UAMCO) is not affiliated with or endorsed by any government agency.
United American Mortgage Corporation | NMLS #1942 | Chris Pessy | NMLS #208346 | Equal Housing Opportunity.
Licensing information: www.nmlsconsumeraccess.org.
Market data references: Freddie Mac Primary Mortgage Market Survey, October 29, 2026; Federal Reserve, October 28, 2026.