Mortgage rates are near 7%, but that may not be your rate. Learn how lender access and 4 financing strategies can help buyers control their payment.
Mortgage Rates Hit 7%. But That May Not Be Your Rate.
4 Ways Buyers Can Take Greater Control of Their Mortgage Payment
7%.
That’s roughly where average 30-year mortgage rates are sitting today.
For many buyers, seeing that number creates an immediate reaction:
“Maybe I should wait.”
But before changing your homebuying plans based on a headline, there’s something important to understand:
The average mortgage rate you see in the news isn’t necessarily the rate available to you.
Your actual mortgage rate can depend on your credit profile, down payment, loan amount, property type, loan structure, points—and importantly, which lender is providing the financing.
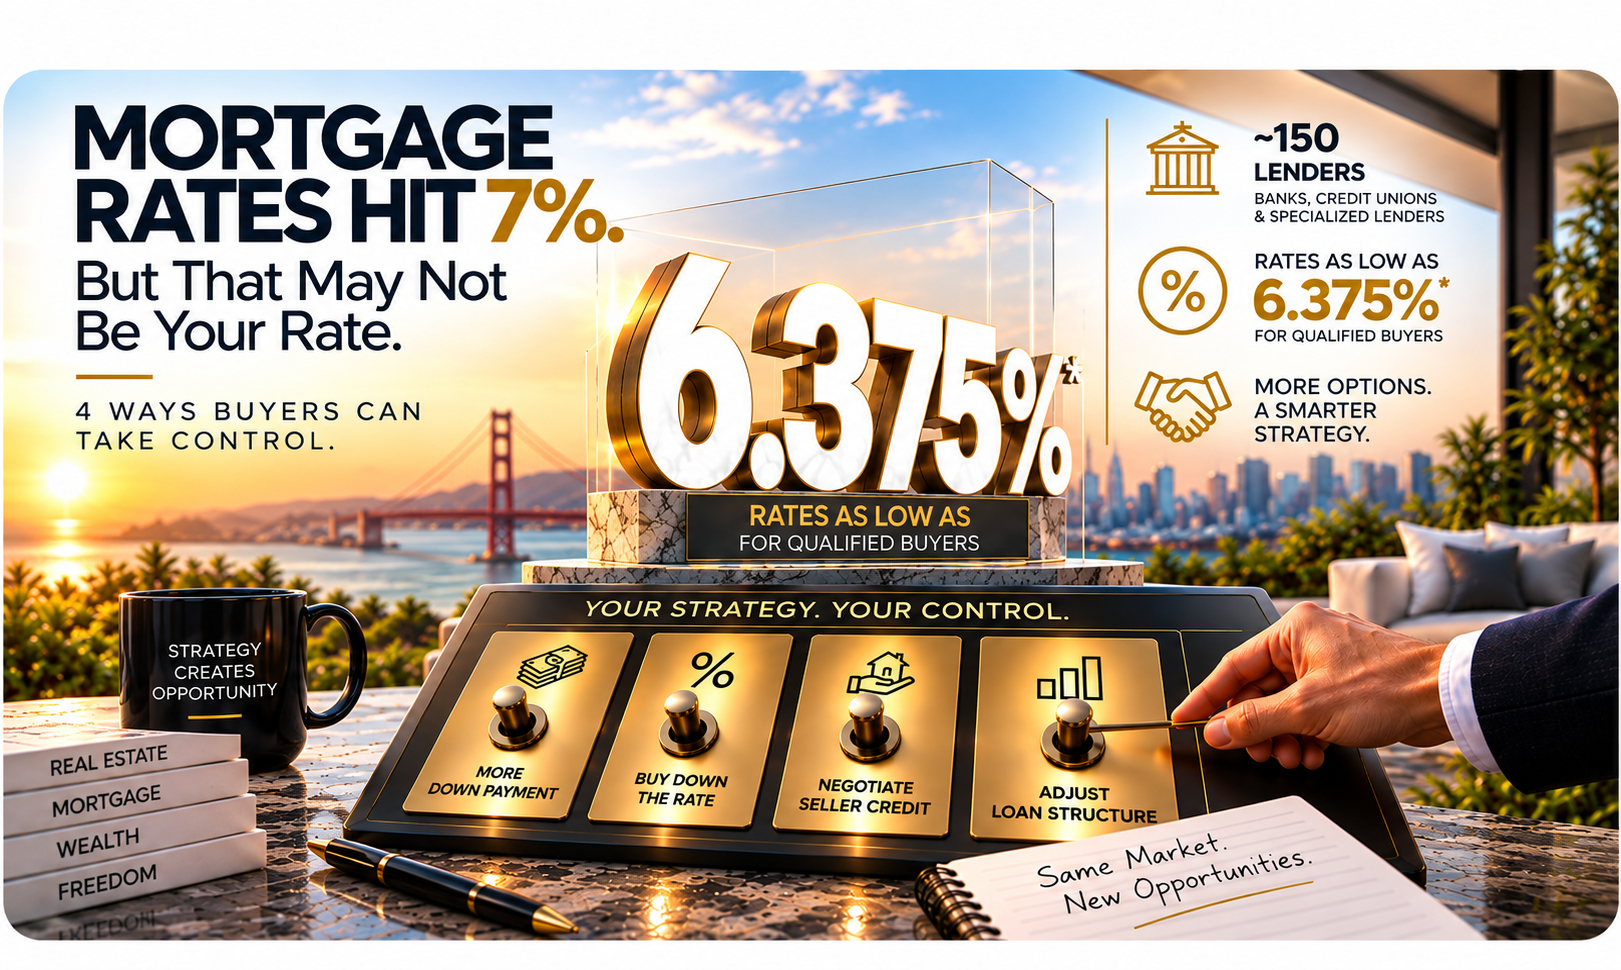
At United American Mortgage, we have relationships with approximately 150 lending sources, including banks, credit unions and specialized lenders.
That creates something a single-bank model simply can't offer:
More places to look for the right financing solution.
While average mortgage rates are around 7%, we currently have options as low as 6.375% for qualified buyers, depending on borrower qualifications, property, loan program, points and other applicable terms.
And finding the right lender is only one part of the strategy.
Because even when you can't control the market, there are several things you may be able to control.
The Market Rate and Your Rate Are Two Different Things
When financial media reports that mortgage rates have reached 7%, they're describing a market benchmark or average.
They're not quoting your mortgage.
Two buyers purchasing similarly priced properties can receive different financing terms based on factors including:
- Credit profile
- Loan-to-value ratio
- Down payment
- Loan amount
- Property and occupancy type
- Loan program
- Points or lender credits
- Relationship pricing
- Lender-specific guidelines and pricing
And lenders themselves don't necessarily price identical scenarios the same way.
That's an important distinction.
If you walk into one bank, you're generally seeing the products and pricing available from that institution.
A mortgage broker with access to a broad network can evaluate the scenario across multiple lending sources.
At UAMCO, that network includes approximately 150 lenders, including credit unions and specialized lending sources.
One market doesn't necessarily mean one rate.
1. Shop the Financing—not Just the Property
Most buyers understand the importance of comparing homes.
Fewer think about comparing the sources of financing with the same level of attention.
But especially in higher-cost markets, lender selection can matter.
Different lenders may have different appetites for:
- Jumbo loans
- High-balance financing
- Condominiums
- Self-employed borrowers
- Asset-based borrowers
- Adjustable-rate mortgages
- Non-QM financing
- Complex income profiles
One lender may be highly competitive for a particular scenario while another may not be.
This is why I don't believe the financing conversation should begin and end with:
“What's your mortgage rate?”
A better question is:
“Which lender and structure are most competitive for my specific scenario?”
When we have approximately 150 potential lending relationships to evaluate, we have significantly more ways to answer that question.
2. Adjust Your Down Payment
Once we've evaluated lender options, the next lever is the down payment.
Increasing your down payment reduces the amount you need to borrow, which can lower your monthly principal-and-interest payment.
But there can be another benefit.
Changing your loan-to-value ratio may also affect mortgage pricing and the programs available to you.
That doesn't mean putting down as much money as possible is always the best strategy.
Cash has value.
Putting another $100,000 into a property might reduce your mortgage payment—but that $100,000 is no longer available for investments, reserves, renovations or other opportunities.
The better question is:
“What down payment gives me the right combination of monthly payment, financing terms and liquidity?”
That's a strategy decision, not simply a down-payment decision.
3. Evaluate the Cost of Buying Down the Rate
Another option is paying discount points in exchange for a lower mortgage rate.
This can make sense in certain situations, but buyers should look beyond the lower rate itself.
The critical calculation is the break-even period.
If paying additional money upfront reduces your monthly payment, how long will it take for those monthly savings to recover the upfront expense?
If you expect to keep the mortgage well beyond that point, the strategy may be worth considering.
If you expect to sell or refinance relatively soon, the economics can look very different.
That's why I don't automatically consider the lowest available rate to be the best financing option.
You need to understand what you're paying to obtain it.
4. Negotiate the Financing Through the Real Estate Transaction
This is where mortgage strategy and real estate strategy intersect.
In a market where buyers may have greater negotiating leverage on certain properties, a seller concession can potentially become part of the financing strategy.
Depending on the transaction and loan program, an eligible seller credit might be used toward items such as:
- Closing costs
- Prepaid expenses
- Discount points
- Temporary rate buydowns
- Other permitted settlement costs
Suppose you have enough negotiating leverage to ask a seller for $15,000.
The instinctive approach might be:
“Reduce the price by $15,000.”
But that's not necessarily the only option.
Depending on the financing, applying some or all of an eligible seller contribution toward closing costs or a rate buydown could potentially produce a different—and sometimes more immediate—financial benefit.
That's why I prefer asking:
“Where will those $15,000 create the greatest value for this buyer?”
Sometimes it's price.
Sometimes it's cash-to-close.
Sometimes it's the mortgage.
And sometimes it's a combination.
5. Consider a Different Loan Structure
The 30-year fixed mortgage is familiar, but it isn't necessarily the only financing structure worth evaluating.
Depending on your financial profile, property, expected ownership period and goals, it may make sense to compare alternatives such as:
- 30-year fixed
- Adjustable-rate mortgages
- Jumbo programs
- Different LTV structures
- Temporary buydowns
- Permanent rate buydowns
- Specialized lending programs
An ARM, for example, isn't automatically better simply because its initial rate might be lower.
You need to understand the fixed period, adjustment schedule, index, margin, caps and potential future payment.
Likewise, a 30-year fixed shouldn't automatically win simply because it's the most familiar option.
The loan should fit your financial strategy—not the other way around.
The Real Opportunity Is Combining the Strategies
These strategies don't necessarily have to be used independently.
Consider what can happen when they're evaluated together.
A buyer could potentially:
Shop across multiple lending sources to identify competitive financing.
Then adjust the down payment to optimize loan amount and pricing.
Negotiate a seller credit.
Use eligible funds toward closing costs or a rate buydown.
And select a loan structure that aligns with the buyer's expected ownership timeline.
That's why the headline “mortgage rates are 7%” tells you surprisingly little about what a specific purchase could actually look like.
There isn't just one lever.
There are multiple moving pieces—and they can work together.
Why This Matters Even More in San Francisco and the Bay Area
In higher-cost markets, small differences can translate into meaningful dollars.
When you're financing a substantial loan amount, differences in rate, loan balance, points, seller contributions and lender pricing can materially affect both monthly payment and cash-to-close.
That's why a buyer considering a $1.5 million or $2 million property shouldn't evaluate the opportunity based solely on a national mortgage-rate headline.
We should be looking at:
What is your actual loan amount?
How much should you put down?
Which lenders are most competitive for your scenario?
Should you pay points?
Can we negotiate a seller contribution?
Which loan structure fits your plans?
And ultimately, what does the complete monthly payment look like?
Those are the numbers that matter.
What About Waiting for Rates to Fall?
Waiting may absolutely be the right decision for some buyers.
If the payment doesn't comfortably fit your financial objectives, you shouldn't force the transaction simply because a property is available.
But there's a difference between:
“The numbers don't work for me today.”
and:
“I heard mortgage rates are 7%, so I'm not buying.”
The first is a financial conclusion.
The second is a conclusion based on an average.
And those aren't necessarily the same thing.
If rates eventually decline, more buyers may also return to the market. Competition, seller concessions and property prices could change.
Or rates could remain elevated longer than expected.
No one can know with certainty.
That's why I prefer to run the buyer's actual scenario today before deciding whether waiting makes sense.
Chris's Market Perspective
When a buyer tells me:
“Rates are 7%, so I'm going to wait,”
my response is simple:
“Let's run your numbers first.”
After more than 25 years in mortgage lending, I've learned that the headline rate rarely tells the complete story.
With access to approximately **150 lending sources—including credit unions and specialized lenders—**we're able to evaluate financing well beyond the offerings of a single institution.
Today, even with average mortgage rates around 7%, we have options as low as 6.375% for certain qualified buyers, subject to the specific borrower, property, loan program, points and market conditions.
As both a Mortgage Advisor and Compass Real Estate Advisor, I also look beyond the mortgage itself.
The property price, seller negotiation, lender selection, down payment, cash-to-close and monthly payment all interact.
The objective isn't simply to find a lower rate.
It's to structure the entire transaction intelligently.
The Bottom Line
7% may be the headline. It doesn't have to be the end of the conversation.
The average market rate isn't necessarily your rate.
And your rate isn't the only variable determining whether a purchase works.
You may be able to:
Shop across multiple lending sources.
Optimize your down payment.
Evaluate a rate buydown.
Negotiate seller credits.
Choose a different loan structure.
Or combine several strategies.
You can't control where the overall mortgage market goes tomorrow.
But you may have considerably more control over your financing and monthly payment than the headlines suggest.
So before deciding to sit on the sidelines:
Run your numbers—not the market average.
What Could Your Actual Rate and Payment Look Like?
If you're considering buying, let's run your scenario before you decide to wait.
We'll evaluate your property, down payment, loan amount, available lending options and potential transaction strategies to determine what the numbers actually look like for you.
And if you know someone who has put their home search on hold because they heard “mortgage rates are 7%,” share this article with them.
The rate they see in the headlines may not be the rate available to them.
This content is for educational purposes only. The 6.375% example is not available to all borrowers and is subject to change without notice. Actual interest rate, APR, points, fees, loan terms and eligibility depend on borrower qualifications, credit profile, property, occupancy, loan amount, LTV, program, lender and market conditions. Seller concessions are subject to applicable loan-program requirements and transaction limits.
The advertised rate of 6.375% (6.473% APR) reflects a 7-year adjustable-rate mortgage (7/6 ARM) available to qualified buyers and is not an offer or commitment to lend.
Rates as low as indicates the lowest rate available to the most qualified applicants; your actual rate, APR, and payment will depend on credit score, loan-to-value, loan amount, occupancy, property type, income, debt, and other factors, and are subject to change without notice until locked. APR shown is an estimated average for illustrative purposes. With a 7/6 ARM, the interest rate is fixed for the first 84 months and thereafter adjusts every 6 months based on the applicable index plus a margin, subject to periodic and lifetime rate caps. Payment examples do not include taxes, insurance, or HOA dues; your actual payment obligation may be higher. All loans are subject to underwriting and investor approval; not all applicants will qualify. This is not a commitment to lend. Programs, rates, terms, and conditions are subject to change without notice. Chris Pessy, SVP of Mortgage Lending, United American Mortgage Corporation (UAMCO), NMLS #208346. Equal Housing Opportunity