63% More Sellers Than Buyers: Where Do Homebuyers Have the Advantage?
October 19, 2026 | Housing Market Insights | Chris Pessy
The U.S. housing market is shifting. But the biggest opportunity may not be where you expect.
What if the most important number in today's housing market isn't the mortgage rate?
What if it's the growing difference between the number of people trying to sell a home and the number of people ready to buy one?
According to a new Redfin report released October 14, 2026, there were approximately 63% more home sellers than buyers nationwide in September.
That's the largest gap in Redfin's records dating back to 2013.
For buyers, this could mean more choices, less competition, and potentially greater negotiating power.
But there's an important catch.
Not every housing market is moving in the same direction.
Miami is among the strongest buyer's markets in the country. San Francisco, on the other hand, remains a seller's market.
So what does this shift actually mean for buyers, sellers, and investors?
And how can the right combination of real estate knowledge and mortgage strategy help you navigate it?
Let's break it down.
1. The Housing Market Is Experiencing a Major Shift
Redfin's September 2026 analysis estimates:
Housing market indicatorSeptember 2026Estimated U.S. home sellers1.51 millionEstimated U.S. homebuyers929,000Sellers relative to buyers62.6% moreMajor metro areas classified as buyer's markets41 of 50
Source: Redfin, October 14, 2026. Figures are estimates based on Redfin's methodology.
This imbalance represents a meaningful change from the intense competition many buyers experienced in previous years.
For much of the recent housing cycle, limited inventory forced buyers to compete aggressively for available properties.
Today, the balance has shifted in many markets.
More homeowners are listing properties, while some potential buyers remain hesitant because of elevated borrowing costs, affordability concerns, and economic uncertainty.
The result?
Buyers in many markets have more properties to choose from—and sellers may need to work harder to attract qualified offers.
However, a national surplus of sellers does not mean every home is overpriced or every seller is motivated to negotiate.
Location, property type, condition, pricing, and local demand still matter enormously.
2. Miami vs. San Francisco: Two Markets, Two Different Stories
Perhaps the most interesting part of Redfin's report is the contrast between South Florida and Northern California.
Miami: Buyers May Have the Upper Hand
Miami recorded approximately 158.9% more sellers than buyers in September 2026, according to Redfin.
That makes it the strongest buyer's market among the 50 major metropolitan areas analyzed.
What does this mean?
For qualified buyers, increased inventory may create opportunities to:
- Compare more properties before making a decision.
- Negotiate purchase prices when listings are competitively challenged.
- Request eligible seller contributions toward closing costs.
- Negotiate repairs or other contractual terms.
- Evaluate properties that have remained on the market longer.
But the opportunity varies significantly across South Florida.
A luxury waterfront property in Miami Beach may behave very differently from a condominium in an area with substantial competing inventory.
Building financials, insurance expenses, condominium assessments, property condition, and financing eligibility can all influence the attractiveness of a particular purchase.
The key takeaway: A buyer's market can create negotiating opportunities, but property-specific due diligence remains essential.
San Francisco: Competition Remains
San Francisco presents a very different picture.
According to Redfin, San Francisco had approximately 10.6% fewer sellers than buyers in September, placing it among the nation's remaining seller's markets.
Limited housing supply and demand associated with the region's technology economy have helped support competition.
For buyers, this can mean:
- Desirable properties may still attract competing offers.
- Pricing strategy remains important.
- Strong financing preparation can help reduce transaction uncertainty.
- Contract terms and closing readiness may influence how an offer is evaluated.
However, not every San Francisco property experiences the same demand.
Single-family homes, condominiums, TIC properties, and multiunit properties can have different buyer pools, financing requirements, and market dynamics.
The key takeaway: Even in a seller's market, a well-prepared buyer can improve their negotiating position by understanding the property and presenting a credible financing plan.
3. Mortgage Rates Remain a Critical Part of the Equation
While buyers may have more negotiating power in certain markets, financing costs remain an important consideration.
According to Freddie Mac's October 15, 2026 Primary Mortgage Market Survey, the average 30-year fixed mortgage rate was 7.40%, unchanged from the previous week.
That compares with 6.27% during the same period one year earlier.
Freddie Mac's survey reflects a defined set of conventional conforming purchase loans and is not a quote for every borrower or property.
Higher borrowing costs affect monthly payments, purchasing power, and the overall economics of a transaction.
But here's what many buyers overlook:
A mortgage rate is only one component of the financial decision.
The negotiated purchase price, down payment, seller contributions, loan program, closing costs, and ongoing ownership expenses can all influence affordability.
That's why I encourage buyers to evaluate the entire transaction before deciding whether a property makes financial sense.
4. Three Opportunities Buyers Should Evaluate Before Making an Offer
In markets where sellers face more competition, buyers may have opportunities to negotiate terms beyond the asking price.
Here are three areas worth examining.
Opportunity #1: Negotiate the Purchase Price
The most obvious strategy is negotiating a lower purchase price.
For example, imagine a home listed at $1,000,000.
If the seller accepts $950,000, the buyer reduces the purchase price by $50,000.
Assuming a 20% down payment, the mortgage principal would decrease by $40,000 compared with purchasing at the original price.
A lower purchase price may also reduce certain transaction costs and future interest expense, depending on the financing structure.
But price reductions aren't always the only option worth considering.
Opportunity #2: Evaluate Seller Concessions
Instead of negotiating exclusively on price, a buyer may request an eligible seller contribution toward closing costs or other permitted financing expenses.
Depending on the loan program, this could help offset certain costs associated with purchasing the property.
For example, seller contributions may potentially be applied toward:
- Eligible lender and closing costs.
- Certain prepaid expenses.
- Discount points.
- An eligible temporary mortgage rate buydown.
Seller contribution limits and permitted uses depend on the applicable loan program, occupancy type, loan-to-value ratio, and lender requirements.
A seller concession does not automatically create additional buying power or make the financing less expensive over the long term.
The value depends on the specific numbers.
Opportunity #3: Compare Financing Structures
Two buyers purchasing the same property may have different financial objectives.
One may prioritize the lowest sustainable monthly payment.
Another may prefer to preserve liquidity.
A third may have significant assets but income that requires specialized underwriting.
Depending on the borrower's qualifications, available options could include:
- Fixed-rate financing.
- Adjustable-rate mortgages.
- Jumbo or portfolio lending.
- Different down payment structures.
- Temporary rate buydowns.
- Certain alternative-documentation or asset-based programs.
Each option carries its own eligibility requirements, costs, and risks.
For example, an adjustable-rate mortgage may offer a different initial payment structure, but future rate adjustments can increase the payment.
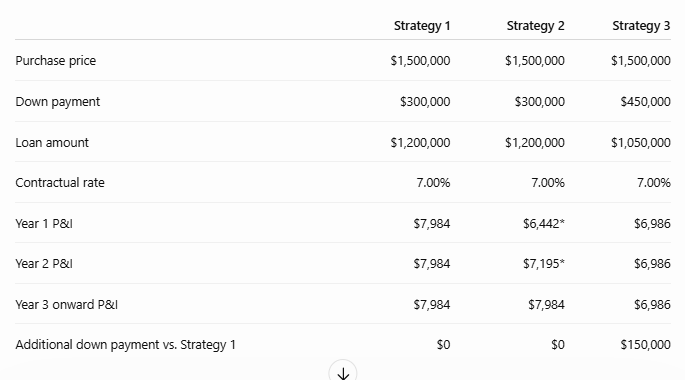
A temporary buydown reduces the borrower's initial payments through a funded subsidy, but it does not change the contractual note rate.
The objective is not simply to find the lowest advertised rate. It's to evaluate the structure that best aligns with the buyer's financial goals.
5. Why a Buyer's Market Doesn't Automatically Mean a Good Deal
More available homes can be beneficial for buyers, but inventory alone doesn't determine value.
Before purchasing, I encourage clients to examine several factors.
Comparable sales: Is the asking price supported by recent transactions involving similar properties?
Days on market: Has the property been listed significantly longer than comparable homes?
Property condition: Are there repairs, deferred maintenance, or upcoming capital expenditures?
Ownership costs: What will property taxes, insurance, HOA dues, assessments, and maintenance actually cost?
Financing eligibility: Will the property qualify for the intended mortgage program?
Long-term objectives: Is the property appropriate for the buyer's expected holding period and financial plans?
These questions are particularly important for condominiums, luxury properties, and transactions involving complex financing.
A discounted property may still be a poor financial decision if the carrying costs, property risks, or financing terms don't support the buyer's objectives.
Likewise, a well-priced property in a competitive market may still represent a sound purchase for the right buyer.
The strongest opportunities are identified through careful analysis—not headlines alone.
6. What Should Sellers Do in This Market?
The growing number of sellers also creates an important lesson for homeowners considering a sale.
In markets with substantial inventory, pricing and presentation become increasingly important.
Sellers may need to consider:
- Pricing based on current comparable sales rather than previous market peaks.
- Preparing the property to compete effectively.
- Understanding the financial profile of likely buyers.
- Evaluating reasonable requests for closing-cost assistance.
- Remaining flexible on terms that could help complete a transaction.
In markets with tighter inventory, sellers may retain more leverage, but accurate pricing and property presentation still matter.
The most effective strategy depends on the local market—not simply the national trend.
7. Chris's Market Perspective: Opportunity Is Local. Strategy Is Personal.
After more than 25 years in mortgage lending and working with thousands of clients across different market cycles, one lesson continues to stand out:
The best real estate decisions are made by understanding the entire transaction—not just one number.
A market with more sellers than buyers may create an opportunity.
But the real question is whether that opportunity makes financial sense for you.
For a buyer in Miami, the conversation may center on inventory, seller flexibility, and the total cost of ownership.
For a buyer in San Francisco, the priority may be competitive positioning, financing readiness, and identifying properties where the asking price is supported by market conditions.
And for high-net-worth buyers, investors, self-employed borrowers, or clients purchasing unique properties, the financing structure may require additional analysis.
Through United American Mortgage Corporation, I have access to more than 150 lending partners, including banks, credit unions, portfolio lenders, and specialty lending sources.
That provides the ability to evaluate a range of potential financing solutions based on the borrower's circumstances.
As a Global Real Estate Advisor with Compass, I also approach transactions from the property and negotiation side.
This combination allows me to consider questions that go beyond the mortgage application:
Is the property priced appropriately?
What terms may be negotiable?
How much capital should the buyer commit?
What loan structure supports the client's financial objectives?
What risks should be understood before moving forward?
The answers will not be the same for every buyer.
And that's precisely why a personalized approach matters.
My perspective: Don't try to predict the perfect time to buy. Focus on understanding the opportunity, the financing, and the financial implications before making your decision.
8. Before You Make Your Next Move, Know Where You Stand
The latest housing data highlights a major change in the national market.
But the most important question isn't whether there are more sellers than buyers across the country.
It's whether your specific market—and the property you're considering—offers an opportunity worth pursuing.
Whether you're buying in Miami, San Francisco, or another market, understanding local conditions and evaluating the financing before making an offer can help you negotiate from a more informed position.
Is Your Market Giving Buyers the Upper Hand?
If you're considering purchasing a property, let's examine the numbers together.
Share the city or neighborhood you're targeting, your approximate purchase price, and your financing objectives.
I'll help you evaluate the local market, potential negotiation opportunities, and financing structures worth considering.
If you're a Realtor, CPA, or financial advisor working with a client evaluating a purchase, I'm also available to review the scenario.
The right opportunity starts with the right information.
Chris Pessy
SVP of Mortgage Lending | United American Mortgage Corporation
Global Real Estate Advisor, CIPS® | Compass
NMLS #208346 | UAMCO NMLS #1942
25+ Years of Experience | 5,000+ Families Supported | 150+ Lending Partners | Nationally Recognized Top 1% Mortgage Originator
Sources and Market Data
- Redfin, October 14, 2026: Home Sellers Now Outnumber Buyers By 63%, the Biggest Gap in at Least 13 Years.
- Redfin, September 2026: Buyer-versus-seller market estimates for major U.S. metropolitan areas.
- Freddie Mac, October 15, 2026: Primary Mortgage Market Survey, 30-Year Fixed-Rate Mortgage Average.
This article is provided for general educational and informational purposes only and does not constitute an offer or commitment to lend, an individualized mortgage quote, or a guarantee of real estate market outcomes. Market statistics are estimates and may differ by source, geography, property type, and methodology. Market conditions, mortgage rates, property values, and loan availability may change without notice. Mortgage rates, loan terms, seller concessions, eligibility requirements, and financing options vary by borrower, property, transaction, and lender. All financing is subject to underwriting, investor requirements, and final approval. Not all applicants or properties will qualify. Temporary mortgage buydowns do not change the contractual note rate and are subject to applicable program guidelines. Chris Pessy, NMLS #208346 | United American Mortgage Corporation, NMLS #1942 | Equal Housing Opportunity.