Learn why purchase price is only part of a homebuying decision and how real estate, financing, negotiation and monthly costs work together.
The Purchase Price Is Only Half the Story
When buying a home, one number naturally gets most of the attention: the purchase price.
But the price you negotiate is only one part of the financial equation.
Two buyers can purchase the same $1 million property at the same price and end up with very different monthly payments, cash requirements, liquidity, and long-term financial outcomes.
That's why a successful real estate purchase shouldn't be measured solely by how much you negotiate off the asking price.
The better question is: How well was the entire transaction structured?
Look Beyond the Purchase Price
Before making an offer, buyers should understand the complete cost and structure of owning the property.
That includes:
- Purchase price and market value
- Down payment
- Interest rate and loan structure
- Property taxes
- Homeowners insurance
- HOA or condominium fees
- Closing costs
- Potential assessments
- Cash reserves after closing
Looking at these factors together provides a much clearer picture of whether a property truly fits your financial and lifestyle goals.
The Lowest Price Isn't Always the Best Deal
Imagine negotiating an additional $20,000 from a seller.
Most buyers would naturally assume the best strategy is simply reducing the purchase price by $20,000.
But that isn't always the case.
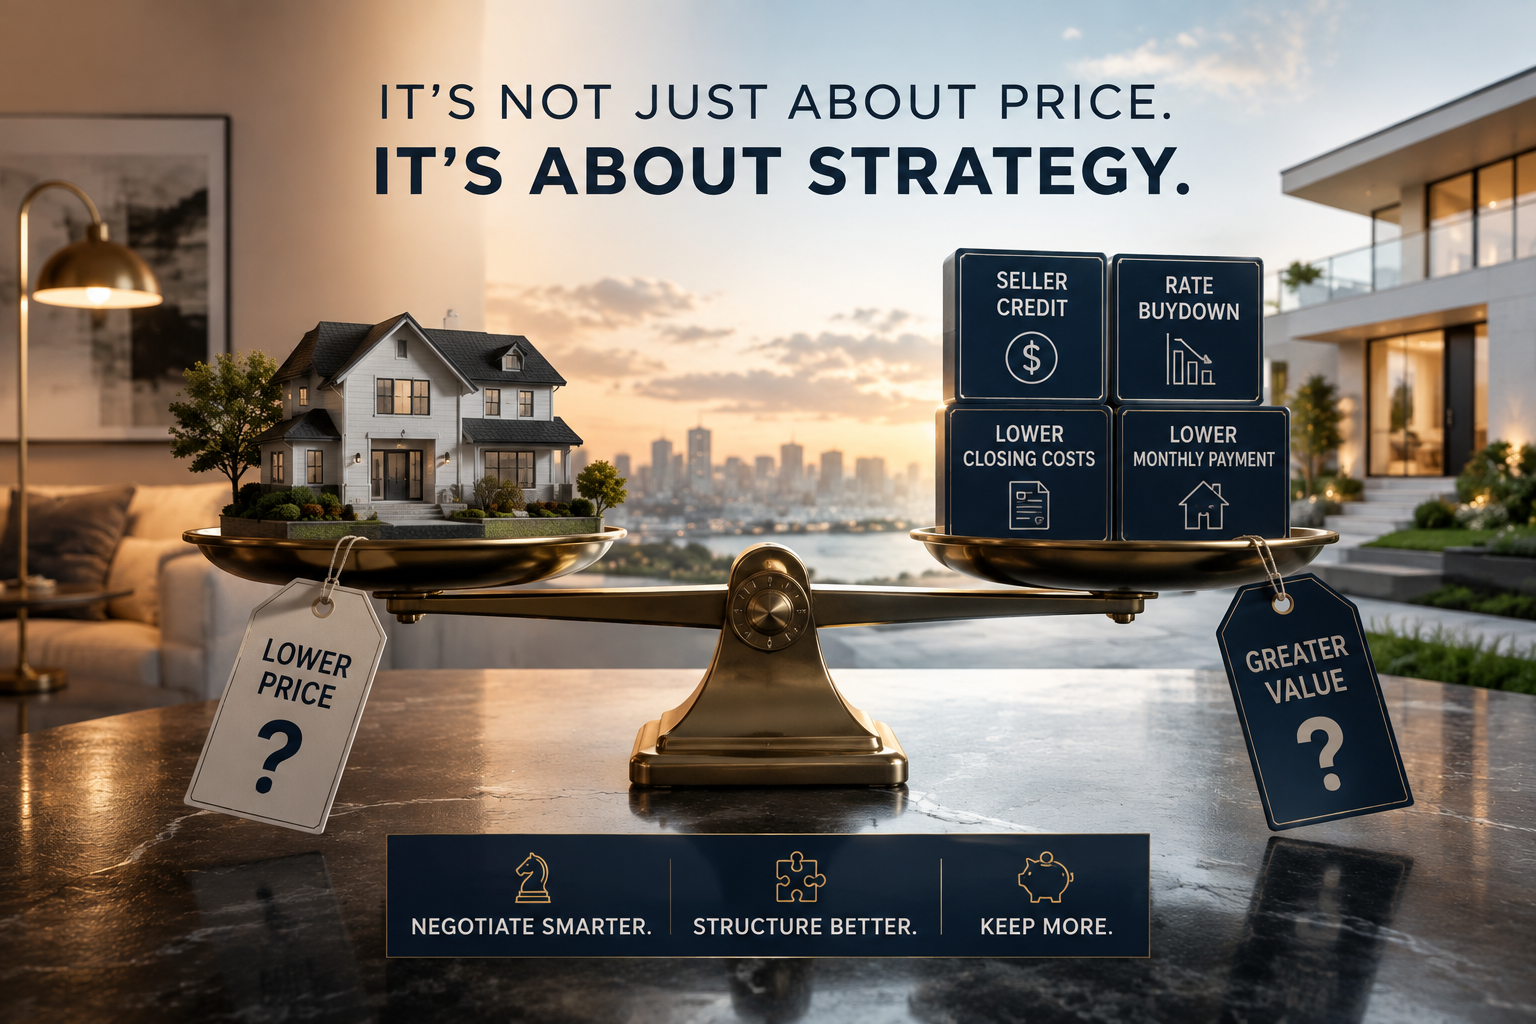
Depending on the transaction and loan structure, that same negotiating leverage might potentially be used toward closing costs or an interest-rate buydown.
One strategy could reduce the amount of cash required at closing. Another could affect the monthly payment. A price reduction may contribute differently to the economics of the transaction.
There isn't one answer that's right for every buyer.
The important point is to evaluate the options before deciding how to negotiate.
How Much Should You Put Down?
Another common assumption is that a larger down payment is always better.
Sometimes it is.
But buyers should also consider what happens to their liquidity after closing.
Putting additional capital into a property may reduce the loan balance and monthly payment, but that same money might otherwise remain available for investments, renovations, reserves, future purchases, or unexpected expenses.
The objective isn't simply to minimize the mortgage.
It's to determine how much capital makes sense to allocate to the property based on your broader financial goals.
Understand the True Monthly Cost
A mortgage payment is only one component of homeownership.
The true monthly cost may also include:
Property taxes + homeowners insurance + HOA fees + assessments + maintenance.
This is particularly important when comparing properties.
A home with a lower purchase price may actually have a higher monthly ownership cost than a more expensive alternative.
For condominium buyers, association fees, reserves, insurance, and potential assessments can materially change the equation.
The asking price alone rarely tells the complete story.
Negotiation and Financing Should Work Together
Real estate negotiations and financing are often treated as separate conversations.
They shouldn't be.
Before making an offer, buyers should understand how different negotiating outcomes could affect the overall transaction.
For example, depending on the circumstances, a seller concession could potentially be directed toward allowable closing costs or financing-related expenses rather than simply reducing the price.
Understanding those options before submitting an offer can help buyers negotiate with a clearer objective.
Don't Forget the Property Itself
Financial structure matters, but attractive financing cannot turn the wrong property into the right investment.
Buyers should still evaluate:
- Location
- Property condition
- Neighborhood trajectory
- Building or community quality
- Comparable sales
- Market demand
- Future resale potential
- Long-term appreciation considerations
A successful purchase requires both sides of the equation to make sense:
the real estate and the financing.
Chris's Market Perspective
I've spent my career looking at transactions from both perspectives, and one principle consistently stands out:
The best purchase isn't necessarily the property with the lowest price or the loan with the lowest rate.
It's the transaction where the property, price, negotiation strategy, financing, liquidity, and long-term objectives work together.
That becomes particularly important in markets where buyers may have greater negotiating leverage.
Instead of asking only, “How much can we get the seller to reduce the price?” I encourage buyers to ask:
“Where can we create the greatest overall value?”
That is a very different conversation—and often a much more valuable one.
Why an Integrated Strategy Matters
As both a Global Real Estate Advisor and Mortgage Advisor, I can evaluate a purchase through two lenses that are normally handled separately.
On the real estate side, that means analyzing value, comparable sales, negotiating leverage, property quality, and resale considerations.
On the mortgage side, it means understanding how down payment, financing structure, seller concessions, and monthly costs affect the transaction.
Bringing those conversations together before an offer is written can provide buyers with a more complete understanding of what they're actually purchasing—and how they should structure it.
Final Thoughts
A home may have one asking price, but there can be many ways to structure the purchase.
The right strategy depends on the property, your financial position, your short- and long-term goals, and the opportunities available within the negotiation.
So before focusing exclusively on the price, look at the complete picture.
Because ultimately, the purchase price is only half the story.
If you're considering purchasing a primary residence, second home, or investment property, I'd be happy to help you evaluate both the real estate opportunity and financial strategy before you make an offer.