Mortgage rates are near 7%, but buyers may have more leverage. Learn how inventory, seller concessions and smart financing can create opportunities.
Mortgage Rates Are Near 7%: Why Today's Buyers May Have More Negotiating Power
When mortgage rates move higher, the natural reaction for many homebuyers is simple:
“Maybe I should wait.”
It's understandable. Higher rates affect monthly payments and purchasing power.
But there's another side of today's housing market that isn't getting nearly as much attention.
Higher rates can also reduce competition—and less competition can create negotiating opportunities for buyers who remain in the market.
That's why I believe buyers should look beyond the mortgage rate and evaluate the economics of the entire transaction.
Higher Rates Are Changing the Market
The latest housing data shows the effect higher borrowing costs are having on buyer activity.
Existing-home sales declined 2% in August to a seasonally adjusted annual rate of 3.98 million.
At the same time, inventory increased to approximately 1.62 million homes, representing 4.9 months of supply.
In simple terms:
Fewer buyers are competing while more properties are available.
That doesn't automatically make every property a good deal. Real estate remains highly local, and desirable homes in strong locations can still attract significant competition.
But in certain markets and for certain properties, the negotiating dynamics have changed.
Less Competition Can Create More Leverage
Think about the difference between two markets.
In a highly competitive market, a buyer may encounter:
Multiple offers.
Offers above asking price.
Limited seller concessions.
Short contingency periods.
Pressure to make decisions quickly.
Now consider a slower market.
A property has been listed for several weeks. The seller hasn't received the offer they expected. There are fewer competing buyers.
Suddenly, the conversation may change.
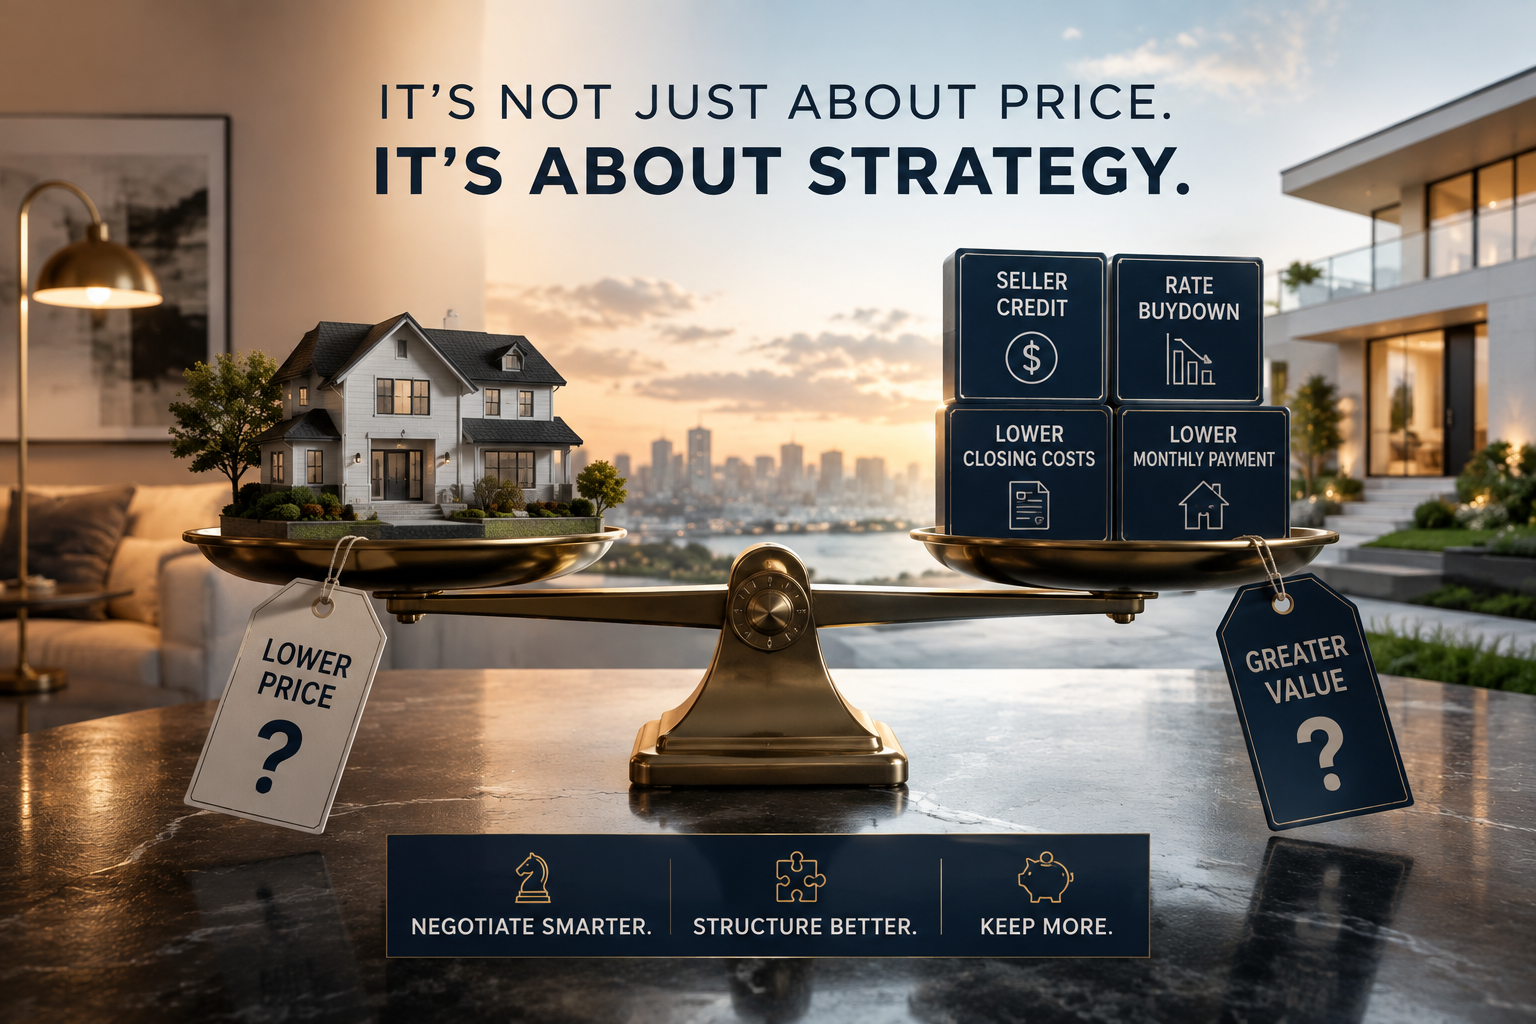
A buyer may have an opportunity to negotiate:
- A lower purchase price
- Seller credits toward closing costs
- Mortgage rate buydowns
- Repairs or improvements
- More favorable contingency periods
- Other terms that improve the economics of the transaction
This is why higher mortgage rates don't necessarily mean there are fewer opportunities.
Sometimes the opportunity simply moves somewhere else in the transaction.
A Lower Rate Isn't the Only Way to Create Value
Buyers naturally focus on mortgage rates because the rate directly affects the monthly payment.
But consider what happens when greater negotiating leverage creates a meaningful seller concession.
Instead of focusing exclusively on reducing the purchase price, a buyer may potentially negotiate a seller credit that can be applied toward eligible closing costs or, depending on the transaction and loan program, a mortgage rate buydown.
That can preserve cash or reduce the cost of financing.
The important point isn't that one strategy is always better.
It's that today's buyers should ask a broader question:
“Where can we create the most value in this transaction?”
Sometimes that's price.
Sometimes it's financing.
Sometimes it's seller-paid costs.
And sometimes it's a combination of all three.
Don't Judge the Market by One Number
This is one of the most important lessons for today's buyer.
A mortgage rate tells you the cost of borrowing money.
It doesn't tell you:
How motivated the seller is.
How much competition exists for the property.
Whether the asking price is negotiable.
Whether the seller will contribute toward closing costs.
Whether repairs can be negotiated.
Whether a rate buydown makes sense.
Or whether you're buying the property at an attractive value.
That's why evaluating a home based solely on the prevailing mortgage rate can provide an incomplete picture.
The rate matters. The transaction matters more.
What About the Federal Reserve?
With another Federal Reserve meeting taking place this week, there will inevitably be headlines about interest rates.
But buyers should understand an important distinction:
The Federal Reserve does not directly set mortgage rates.
Mortgage rates are influenced by the broader bond market, including Treasury yields, inflation expectations, economic data and investor expectations about where monetary policy and the economy are headed.
Markets often begin adjusting to anticipated Federal Reserve decisions before the Fed actually announces anything.
That's one reason trying to perfectly predict the next move in mortgage rates can be so difficult.
Rather than asking:
“What will rates be three months from now?”
I prefer a more useful question:
“Does the opportunity available today make financial sense?”
The Risk of Waiting for the “Perfect” Rate
Suppose a buyer waits because they believe mortgage rates will eventually decline.
They might.
But what happens if lower rates bring more buyers back into the market?
Competition could increase.
Seller concessions could decrease.
Properties could receive multiple offers again.
Prices could respond to stronger demand.
In that scenario, the buyer may obtain a better mortgage rate—but have less negotiating power on the property.
Of course, the opposite can happen as well.
That's precisely the point.
There is no single variable that determines whether it's a good time to buy.
The decision should depend on the buyer's financial position, the property, local market conditions, financing options and negotiating opportunity.
Look for Opportunity, Not Just Lower Rates
Today's market may reward buyers who are prepared and selective.
That doesn't mean rushing into a purchase simply because a seller is willing to negotiate.
It means recognizing that a slower market can give buyers something valuable:
Time and leverage.
More time to evaluate the property.
More opportunity for due diligence.
More ability to negotiate.
And potentially more ways to structure the transaction intelligently.
The goal isn't to buy because rates are high.
The goal is to recognize when higher rates have created an opportunity elsewhere.
Chris's Market Perspective
Headlines focus on mortgage rates.
I focus on the entire transaction.
Higher rates absolutely affect affordability—but they can also change competition, seller motivation and negotiating leverage.
As both a Mortgage Advisor and Compass Real Estate Advisor, I evaluate what a buyer is paying for the financing and what they're paying for the property.
Sometimes a less competitive market can create opportunities that aren't visible in the interest rate alone.
That's why I don't believe buyers should ask only:
“Is this a good rate?”
They should also ask:
“Is this a good property, at a good value, with a financing and negotiating strategy that makes sense for me?”
When those pieces work together, the opportunity can look very different.
The Bottom Line
Mortgage rates near 7% aren't insignificant. They affect purchasing power and should be factored carefully into any buying decision.
But they don't tell the whole story.
Today's market is also providing buyers in many areas with more choices and potentially greater negotiating leverage.
The best opportunity may not come from waiting for the perfect mortgage rate.
It may come from finding the right property, negotiating the right terms and structuring the financing intelligently.
Because successful real estate decisions aren't made by focusing on one number.
They're made by understanding the complete picture.
Considering a Purchase?
Let's identify where today's market may create an advantage for you.
This content is for educational purposes only. Real estate markets, mortgage rates, loan programs, seller concessions and financing terms vary by property, borrower, location and market conditions.